"What is my home worth?" sounds like a simple question. In Miami, the honest answer is: it depends on who is asking, why they are asking and which numbers they are looking at. An online estimate, a property appraiser's assessment, a bank appraisal and a Realtor's market analysis can all give you a different figure for the same property, sometimes tens of thousands of dollars apart.
This guide explains how home valuations really work in Miami in 2026, what drives the price of a single-family home or a condo in Miami-Dade right now, why online estimates often miss, and how to get a number you can actually make decisions with, whether you are planning to sell this year, refinance, or simply want to know where you stand.
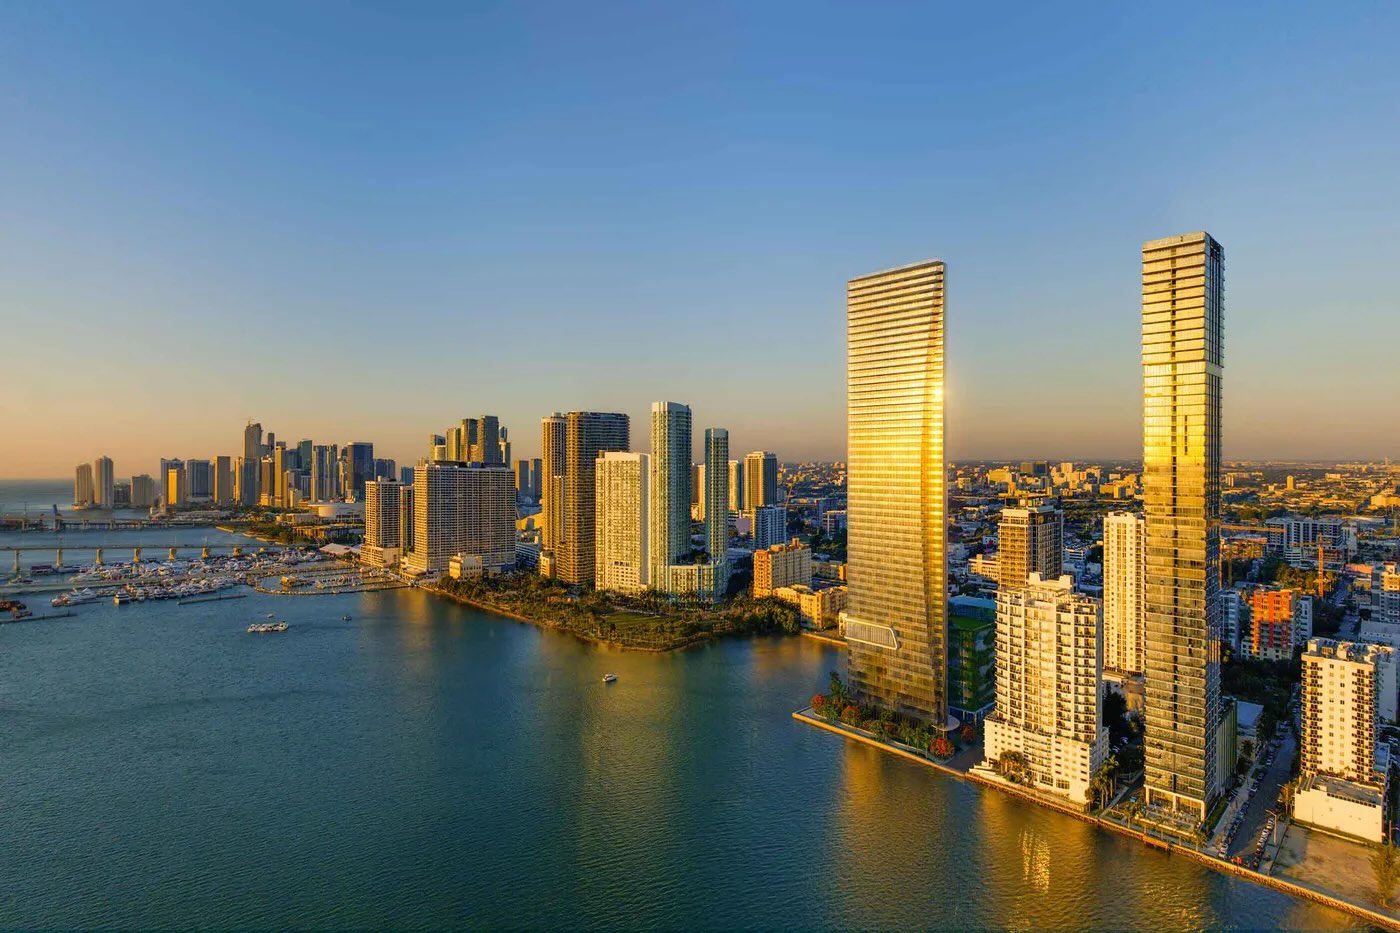
Two homes a few blocks apart in Miami can be worth very different amounts. Location, condition and the building matter more than any national average.
The Miami Market in Fall 2026: The Context Behind Your Number
Every valuation starts with the market. According to the MIAMI REALTORS® report released on October 16, 2026, the median sale price for a single-family home in Miami-Dade reached $692,000 in September 2026, up about 4% from $665,000 a year earlier. Closed single-family sales dipped slightly to 824, and active single-family inventory was down roughly 17% year over year, which keeps pressure on prices for well-located houses.
Condos tell a different story. The countywide condo median was about $417,000, roughly flat (down less than 1%) from a year earlier. Condo inventory has been falling, but summer reports still showed around 11 to 12 months of supply, well above the six to nine months usually considered a balanced market. In other words, condo buyers still have choices and time to compare.
Financing is the other half of the picture. Freddie Mac's 30-year fixed-rate average was 7.40% for the week of October 15, 2026, up from the mid-6% range a year earlier. Higher rates reduce what many buyers can afford each month, which matters most in the price ranges where buyers rely on a mortgage.
| Miami-Dade, September 2026 | Single-family homes | Condos & townhomes |
|---|---|---|
| Median sale price | $692,000 (+4% YoY) | About $417,000 (−1% YoY) |
| Inventory trend | Down about 17% YoY | Falling, but still high supply |
| Who has the edge | Sellers in most price ranges | Buyers in many buildings |
What this means for you: a county median is not your home's value. It only tells you the direction of the market. A three-bedroom house in Coral Gables and a two-bedroom condo in an older tower in North Miami live in completely different markets, even though both feed into the same Miami-Dade numbers.
The Four "Values" You Will Hear About (and Why They Differ)
Homeowners are often confused because they see several numbers attached to the same property. Each one is built for a different purpose.
1. Online estimates (AVMs)
Sites like Zillow, Redfin and Realtor.com use automated valuation models (AVMs). These algorithms look at public records, recent sales nearby and listing data, then produce an estimate in seconds. They are useful as a starting point and for tracking trends, but they cannot see inside your home. They do not know that you renovated the kitchen, that your unit faces the bay instead of the parking garage, or that your building just approved a large special assessment.
In Miami, AVMs tend to struggle most with condos (where floor, view and building health change everything), waterfront properties, unique architecture and luxury homes, where there are fewer comparable sales.
2. The property appraiser's "just value"
The Miami-Dade Property Appraiser assigns every property a market ("just") value as of January 1 each year for tax purposes. That number usually lags the market, and it is not designed to tell you what a buyer would pay today. If you have a homestead exemption, your assessed value (the one used to calculate taxes) can be far below market value because Florida's Save Our Homes rule limits how much it can increase each year. Never price a home off your tax bill.
3. A bank appraisal
When a buyer uses a mortgage, the lender orders an appraisal from a licensed, independent appraiser. The appraiser inspects the property and compares it with recent closed sales to protect the lender's loan. Appraisals tend to be conservative, because they rely on what has already closed, not on what buyers are willing to pay this month. If the appraisal comes in below the contract price, the buyer may need to bring more cash, renegotiate or walk away, depending on the contract.
4. A Comparative Market Analysis (CMA)
A CMA is what a Realtor prepares to help you price a home for sale. It combines recent closed sales, current competition, pending deals and expired listings, then adjusts for the details that algorithms miss: condition, upgrades, view, lot, floor, building finances and the current pace of the market. A good CMA does not just tell you a number; it tells you a pricing strategy and what it is likely to net you.
| Valuation | Who prepares it | Best used for | Main limitation |
|---|---|---|---|
| Online estimate (AVM) | Algorithm | Quick reference, trends | Can't see condition, view or building issues |
| Property appraiser value | Miami-Dade County | Property taxes | Lags the market; not a sale price |
| Bank appraisal | Licensed appraiser | Mortgage approval | Conservative; backward-looking |
| CMA | Realtor | Pricing a sale | Only as good as the agent's local knowledge |
What Actually Drives Home Values in Miami
Beyond the market as a whole, these are the factors that most often move a Miami valuation up or down.
Location, down to the street
Miami prices change block by block. School boundaries, distance to the water, flood zone, noise from major roads, walkability and the feel of the street all matter. In neighborhoods like Coral Gables or Coconut Grove, two houses of the same size can sell for very different prices because one sits on a quiet, tree-lined street and the other backs onto a busy road.
Water, views and elevation
Waterfront and water-view properties carry a clear premium in Miami, but buyers now look closely at elevation, flood history and insurance costs. A home that has never flooded, sits higher than its neighbors or has updated impact windows and a newer roof is easier to insure, and that shows up in what buyers are willing to pay.
Condition and updates
Renovated kitchens and bathrooms, impact windows and doors, a newer roof, updated electrical and A/C systems all add value, especially when they reduce a buyer's insurance or repair costs. Cosmetic updates help a home sell faster; system updates help it appraise.
For condos: the building is part of the value
Since Florida's post-Surfside condo safety laws, buyers and lenders examine a building's milestone inspection, its Structural Integrity Reserve Study (SIRS), reserves, insurance, pending special assessments and litigation. Two identical units in two different towers can be worth very different amounts if one building is well funded and the other has a large assessment coming. Some buildings have also become harder to finance, which limits the pool of buyers. I explain this in detail in Miami's condo financing crisis in 2026.
Floor, line and exposure
Within the same condo building, higher floors, corner units, bay or ocean views and better layouts can command a meaningful premium. That is why the best comparable sale for a condo is usually another unit in the same "line" (the same position on a different floor) of the same building.
Carrying costs
Buyers in 2026 calculate the full monthly cost: mortgage, HOA dues, property taxes and insurance. High HOA dues or expensive insurance reduce what a buyer can pay for the property itself. When you understand your home's carrying costs, you understand part of its value.
How a Professional Valuation Works, Step by Step
When I prepare a valuation for a Miami homeowner, this is the process I follow.
- Visit the property.Photos and public records never tell the full story. Layout, light, condition, noise and views all affect price.
- Pull closed sales.Usually from the last three to six months, as close as possible in location, size, age and style. For condos, ideally in the same building or in directly competing buildings.
- Study the competition.Active listings show what buyers will compare your home with today. Pending sales show what is moving right now.
- Learn from expired listings.Homes that did not sell reveal the price level buyers rejected.
- Adjust for differences.Pool, renovation, lot, floor, view, parking, building finances and more.
- Read the pace of the market.Days on market, price reductions and the ratio of sale price to list price in your segment.
- Build a pricing strategy and a net sheet.A suggested list price, a realistic sale range, and an estimate of what you would keep after closing costs.
A valuation is a range, not a single number. The goal is to know where buyers are likely to respond and where they will not. Pricing a little above that range "to leave room to negotiate" usually backfires in Miami, because buyers compare your home with every similar listing online.
Why Online Estimates Often Miss in Miami
Here are the most common reasons I see automated estimates get a Miami property wrong:
- Mixed building quality. An algorithm may treat a unit in a well-funded tower and one in a building facing a major assessment as equal.
- Views and exposure. A direct bay view versus a city view can be worth a lot, and public records usually do not capture it.
- Unrecorded renovations. Many updates never show up in the data an AVM reads.
- Few comparable sales. Waterfront homes, estates and unique architecture simply do not have many recent comps.
- Fast-changing segments. When a segment shifts, such as older condos in 2025 and 2026, algorithms that lean on older sales can be slow to catch up.
Use online estimates as a conversation starter, not as a pricing decision.
What You Can Do Now to Increase Your Home's Value
If you are thinking about selling in the next few months, small actions can make a real difference in what buyers offer.
- Fix the obvious. Leaks, damaged floors, broken fixtures and anything an inspector will flag.
- Gather documents. Permits for past work, roof and A/C dates, wind-mitigation and four-point inspections, warranties. In Miami, these documents can lower a buyer's insurance quote and support your price.
- For condos, get the building information early. Milestone inspection status, SIRS, reserves, budget, assessments and rental rules. Buyers will ask.
- Neutral paint, lighting and a deep clean. Inexpensive, and they photograph well.
- Professional photography. Almost every buyer starts online. Weak photos cost showings.
- Avoid over-improving. A large renovation only makes sense if comparable renovated homes sell for clearly more than it costs.
From Value to Net Proceeds: What You Actually Keep
The sale price is not what lands in your bank account. Before you decide to sell, estimate your net. In Miami-Dade, a seller typically plans for:
- Real estate commission (negotiable).
- Documentary stamp tax on the deed, customarily paid by the seller: in Miami-Dade, $0.60 per $100 of the price for single-family homes and $1.05 per $100 for other properties such as condos.
- Title, settlement and lien search fees, plus an estoppel fee for condos and HOA properties.
- Prorated property taxes and association dues.
- Your mortgage payoff.
If you are selling a condo, my step-by-step guide to selling a Miami condo in 2026 covers these costs in more detail, including FIRPTA for international sellers.
Single-Family Homes vs. Condos: Two Different Valuation Conversations
Single-family homes in most Miami-Dade price ranges remain in a relatively tight market. With inventory down and prices up year over year, well-presented houses in good locations still attract solid interest. The valuation conversation here focuses on recent sales on comparable streets, condition, lot and insurance costs.
Condos require more homework. With higher supply and buyers who scrutinize every building's finances, the valuation conversation focuses on your building's position: its reserves, assessments and financing status, how your unit compares with others for sale in the same tower, and what competing buildings nearby are offering. A precise, building-specific analysis matters more here than anywhere else. If you want a sense of how prices vary across one of Miami's most active condo markets, see how much a condo in Brickell costs in 2026.
Should You Sell Now or Wait?
Nobody can promise where prices will be next year. What you can control is the quality of your decision. A few questions to ask yourself:
- What would I net if I sold at a realistic price today?
- What does it cost me each month to keep the property (dues, taxes, insurance, maintenance, mortgage)?
- Is my building facing assessments or repairs that could affect value in the next year or two?
- Would renting it out make more sense than selling, after all costs?
- What is my next move, and how does the timing of this sale affect it?
For many owners, the clearest answer comes from putting real numbers side by side: a valuation, a net sheet and a rental estimate. You can also read my overview of Miami house prices in 2026 for more market context.
Frequently Asked Questions
How accurate is Zillow's estimate for my Miami home?
It can be a useful reference, but it often misses for Miami condos, waterfront homes and renovated properties because the algorithm cannot see condition, views or building finances. Use it as a starting point and confirm with a professional analysis.
Why is my property appraiser value lower than what homes are selling for?
The Miami-Dade Property Appraiser values property as of January 1 for tax purposes, and that figure often lags the market. If you have a homestead exemption, your assessed value is also capped by Florida's Save Our Homes rule, so it can be well below market value.
What is the difference between an appraisal and a CMA?
An appraisal is ordered by a lender and completed by a licensed appraiser to support a mortgage. A CMA is prepared by a Realtor to help you price your home for sale, and it also considers current competition, pending sales and market pace.
How much is the median home in Miami-Dade worth right now?
In September 2026, the median sale price was $692,000 for single-family homes and about $417,000 for condos, according to MIAMI REALTORS®. Your property's value can be very different, depending on its location, condition and, for condos, the building.
Does a free home valuation obligate me to sell?
No. A valuation simply gives you information. Many owners request one to plan a sale months in advance, to decide between selling and renting, or to understand their equity.
This article is for general information only and is not an appraisal, legal or tax advice. Market figures come from MIAMI REALTORS® (September 2026 report) and Freddie Mac (week of October 15, 2026) and may change. Contact me for an analysis of your specific property.
Want to Know What Your Miami Home Is Worth?
I will prepare a free, no-obligation valuation built around your property, your street or your building, and the current market, along with an estimate of what you would net if you sold. If you are not ready to sell, that is fine: knowing your number helps you plan your next move with confidence. You can also learn more about how I help owners on my Miami home sellers page.
Get Your Free Home Valuation
A clear price range, a pricing strategy and an estimated net sheet for your Miami property. No obligation.
Get My Free Valuation